What New York City’s Commercial Rent Tax Charges Manhattan Tenants
Tenants in Manhattan with at least $250,000 in annual base rent owe a 3.9% effective tax, but available credits can reduce what they actually pay.
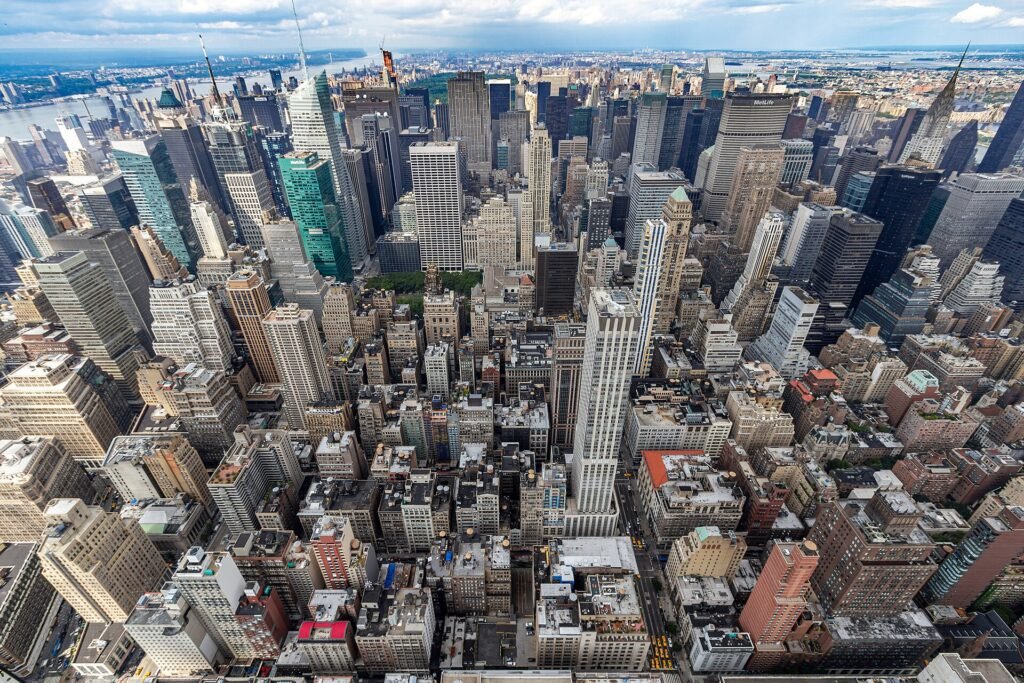
New York City’s commercial rent tax is a tax charged to business tenants—not landlords—on space they occupy in Manhattan south of 96th Street. The tax applies only to tenants with annualized base rent of at least $250,000. All businesses paying less than that amount are exempt, regardless of industry or profitability.
For small businesses on the cusp of the $250,000 threshold, the tax matters significantly. Understanding how the threshold works, how the rate is calculated, and which credits apply can mean tens of thousands of dollars in difference on a multi-year lease. The tax was reformed in 2017 to benefit small businesses, creating a tiered credit system based on income and rent levels.
A Tax Unique to New York City
The tax was first introduced in 1963 to increase tax revenue by shifting more of the tax burden to businesses instead of raising sales taxes on residents. The tax is technically imposed citywide, but an exemption limits it in practice to Manhattan south of the center line of 96th Street.
Most recently, in 2017, the New York City Council passed significant changes aimed at reducing the tax burden on small businesses and retail.
Commercial rent tax at a glance
The tax applies to tenants in Manhattan south of 96th Street paying $250,000 or more annually in base rent. The effective rate is 3.9% after a 35% base rent reduction. Businesses with income under $5 million and base rent under $500,000 qualify for full exemption. Businesses must file a return if they pay more than $200,000 in annualized gross rent, with annual returns due June 20.
Geographic Scope and the $250,000 Threshold
The commercial rent tax is imposed on every tenant—defined as a lessee, sub-lessee, licensee, concessionaire, or co-op tenant-shareholder—occupying commercial space in Manhattan south of the center line of 96th Street. The geographic boundary is precise: properties north of 96th Street and all properties in the other four boroughs are exempt.
The tax applies when annualized base rent reaches $250,000 or more. Businesses paying less than $250,000 a year in base rent are completely exempt from the tax. The threshold is based on annualized rent, meaning a tenant signing a lease at $21,000 per month ($252,000 annually) enters the tax system, while one paying $20,000 monthly ($240,000 annually) stays exempt.
The threshold is rigid and immediate. There is no phase-in period or exemption for new businesses. A startup moving to Manhattan and signing a $300,000 annual lease is liable from the first tax period. However, the law does provide a sliding-scale credit for businesses in the $250,000 to $300,000 range, which can significantly reduce or eliminate actual tax owed.
How the Tax Rate and Base Rent Calculation Work
The nominal tax rate is 6% of base rent. However, the law provides a statutory 35% reduction to all taxpayers on their base rent before the tax is calculated. This means only 65% of base rent is subject to tax, reducing the effective rate to 3.9%. On a $250,000 lease, the annual tax works out to approximately $9,750 before any credits are applied.
Base rent is calculated by starting with the total amount paid to the landlord and then subtracting specific items. Base rent includes not only the lease payment but also charges for real estate taxes, water and sprinkler charges, electricity if sub-metered, work allowances, and rent escalations. Billboards on a leased property are also included in base rent.
The calculation accounts for subleasing. If a tenant sublets part of the space to another business, the rent received from that subtenant can be deducted from base rent before the tax is calculated. This deduction applies regardless of the amount of subrental income. For example, a tenant leasing 5,000 square feet at full capacity might owe $12,792 in tax on a lease large enough to trigger the tax, but by subleasing just three offices for $2,500 monthly, that same tenant could reduce their net base rent enough to owe zero tax by staying below the $250,000 threshold.
Certain items do not count toward base rent. Tenant-paid improvements, maintenance of space, and rents from buildings in designated commercial revitalization programs are excluded. These exclusions can matter for tenants who negotiate build-out costs or ongoing maintenance responsibilities as part of the lease.
Filing Requirements and the $200,000 Floor
Tenants with annualized gross rent paid of more than $200,000 must file a commercial rent tax return, even if they owe no tax. This means a business below the $250,000 threshold for actual tax liability must still report if rent exceeds $200,000.
Annual returns covering the tax year from June 1 to May 31 are due on June 20. Quarterly returns are due on September 20, December 20, and March 20. The filing requirement exists separately from the tax liability threshold. A tenant paying exactly $210,000 annually has no tax owed but is legally required to file a return to confirm exemption status.
Failure to file when required can result in penalties and interest. Credits must be claimed on filed returns; they are not granted automatically.
The commercial rent tax functions as a hidden cost on lease negotiations below 96th Street.
Credits for Small Businesses
The 2017 reforms established a tiered credit system based on business income and base rent levels. The system created what amounts to an expanded exemption for many small businesses that would otherwise owe tax.
Businesses with total annual income of $5 million or less and base rent below $500,000 receive complete exemption from commercial rent tax liability. This exemption applies even if base rent exceeds $250,000, as long as both conditions are met. The reform was estimated to reduce commercial rent tax liability for 2,700 small businesses, including 1,800 that would no longer pay the tax at all.
A separate sliding-scale credit applies to businesses that do not qualify for full exemption. This credit is calculated using two independent factors: an income factor that phases down as income rises from $5 million to $10 million, and a rent factor that phases down as base rent rises from $500,000 to $550,000. For example, a business with $7.5 million in total income and $525,000 in base rent receives a credit equal to one-quarter of the tax owed. Businesses earning over $10 million receive no credit.
The standard credit for tenants in the $250,000 to $300,000 base rent range phases out linearly as rent increases within that band. At $300,000 and above, this standard credit no longer applies, and only the small business credit becomes available. Average annual tax relief for businesses that qualify for the small business credit was estimated at $11,300 to $13,000 per year.
Exemptions Beyond the Threshold
Several classes of tenants are fully exempt from the commercial rent tax regardless of how much rent they pay. Nonprofit religious, charitable, and educational organizations are exempt; other nonprofits may qualify for exemption with written approval from the Department of Finance. Governmental bodies are exempt. Premises occupied 14 days or fewer in a year are exempt, which protects temporary event spaces and short-term commercial uses.
Tenants who use at least 75% of their floor space to rent to others for residential purposes are exempt from the tax, though this exemption does not apply to hotel operators. Certain theatrical productions are exempt for their first 52 weeks of operation. Premises in designated commercial revitalization areas are exempt, as are premises located in the World Trade Center Area, which receives special tax treatment.
These exemptions operate independently of the income and rent thresholds. A nonprofit paying $500,000 annually in base rent owes nothing. A government agency paying $1 million annually owes nothing. But a for-profit business in the same building at the same rent level would owe tax unless it qualifies for a credit.
Why the Tax Shapes Lease Negotiations
The commercial rent tax functions as a hidden cost on lease negotiations below 96th Street in Manhattan. Because the tax is substantial and takes effect immediately upon crossing the $250,000 threshold, the threshold can shape how a lease near that level is negotiated.
The tax is charged to tenants, not landlords. Landlords typically do not pay it or deduct it from tenant rent. The burden falls entirely on the occupying business. For small businesses in high-demand Manhattan neighborhoods, the additional 3.9% cost on top of market rent can determine whether a location is affordable. A difference of $1,000 per month in rent can mean the difference between owing tax and staying exempt.
Photo: Nico Serrano · CC BY-SA 3.0 · via Wikimedia Commons